This ₹1,200 crore fund manager has an advice for Vedanta Aluminium - Here's what he said
Resumen detallado
Trading at just under five times its projected EBITDA on conservative LME assumptions, the Vedanta Aluminium stock offers a compelling risk-reward ratio. While Parekh noted that predicting whether LME prices will swing toward $2,500 or $3,000 is difficult, his demand-supply analysis indicates prices are unlikely to see a sharp downturn.
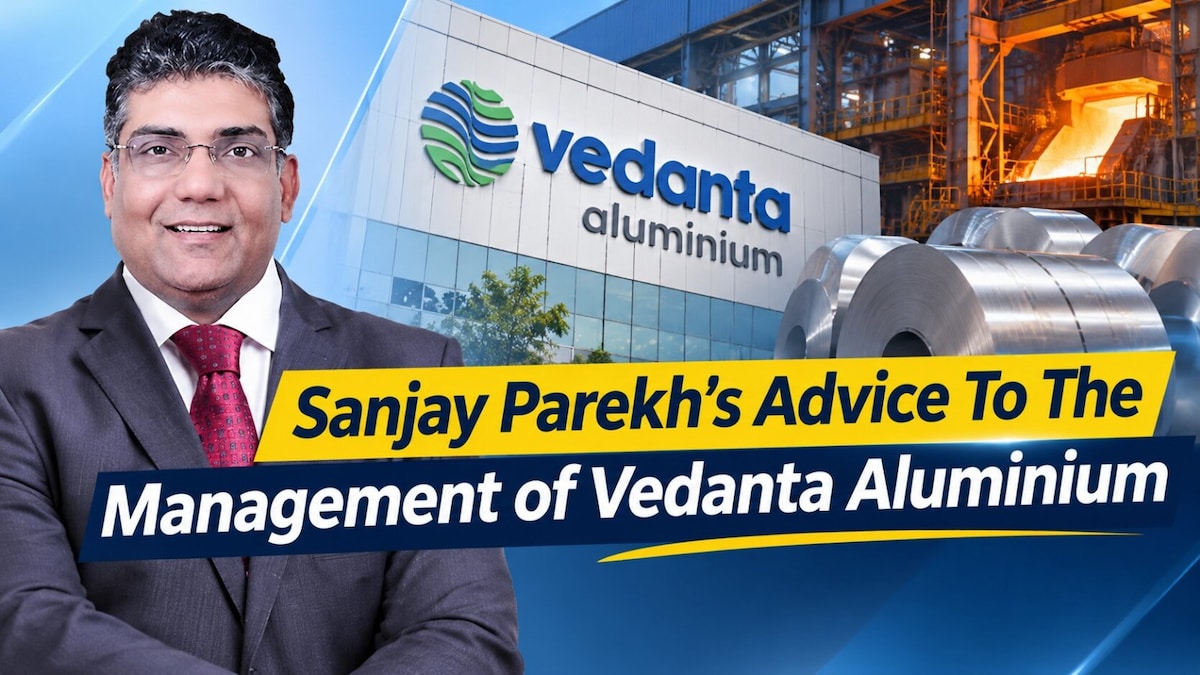
Sanjay Parekh, Founder & CIO of Sohum Asset Managers, believes the management of Vedanta Aluminium should initiate a meaningful share buyback, calling the stock an "amazingly deep value" play.
According to Parekh, the company's strong cash flow allows it to reward shareholders via both buybacks and dividends while still becoming completely debt-free within the next two to three years.
He went on to explain the valuation math during an interaction with CNBC-TV18 on Wednesday, November 18:
Parekh mentioned that Vedanta Aluminium currently has a market capitalization of ₹1.43 lakh crore. Against that, the business has a debt of ₹20,000 crore for the current year. He went on to add that even after funding capital expenditure and paying dividends, the company is paring down debt at a rate of ₹2,500 crore to ₹3,000 crore per quarter.
Assuming that the London Metal Exchange (LME) aluminium prices sit at $2,800 per tonne, Parekh estimates Vedanta Aluminium to generate an attributable Earnings Before Interest, Tax, Depreciation and Amortisation of ₹33,000 crore to ₹34,000 crore on 2.5 million tonnes of production. This is aided by value-added products and the expiration of previous loss-making hedges.
Trading at just under five times its projected EBITDA on conservative LME assumptions, the stock offers a compelling risk-reward ratio. While Parekh noted that predicting whether LME prices will swing toward $2,500 or $3,000 is difficult, his demand-supply analysis indicates prices are unlikely to see a sharp downturn.
The business boasts a Return on Capital Employed (ROCE) of over 50%, with Return on Equity (ROE) expected to climb even higher. Having already paid a dividend of ₹8 per share, Parekh sees scope for payouts to rise as high as ₹20 per share alongside a potential share repurchase program.
"This is a time when the management should meaningfully do a buyback, and they can pay dividends, buy back, and yet in two three years the debt will be free, it will be debt free, it’s…
Sh…
Inicio del artículo, extracto de CNBC-TV18. Para leer el resto, abra el artículo en el sitio del medio.
MarketNews muestra el titular y el resumen publicados por el medio. El artículo completo se lee en el sitio del editor. (www.cnbctv18.com)