David Jones suppliers in the dark until next year as debt blows past $419m
Detailed summary
The financial damage from the department store’s collapse is expected to exceed half a billion dollars in debts to its private equity owner, lender, landlords, suppliers and staff.
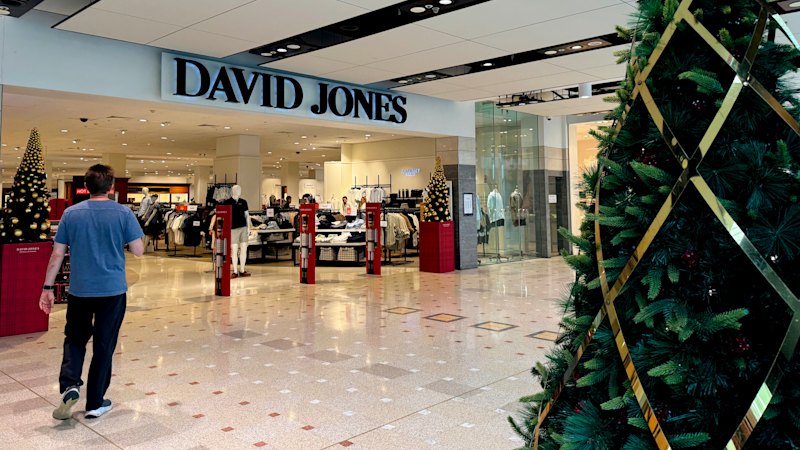
Nearly a thousand suppliers left out of pocket from David Jones’ collapse will be forced to wait until next year to find out how significant their losses will be as administrators seek a buyer to take on the 188-year-old retailer with debts expected to blow past the half-a-billion-dollar mark.
More than 500 suppliers who joined David Jones’ first creditors’ meeting via Zoom on Tuesday morning received little assurance they would get their money back, as administrators McGrathNicol revealed the department store owed $419 million to various parties when it collapsed.
This figure does not include potential claims for unpaid rent and additional expenses from landlords, and the significant cost of paying redundancies for thousands of staff who will lose their jobs as half the group’s stores close. The employee payments will rank ahead of suppliers’.
Suppliers are unlikely to find out how much of their debt they can recoup until mid to late January, after administrators have had time to shortlist and then negotiate with potential bidders for David Jones in December. Deadlines for expressions of interest were due last Friday afternoon.
Representatives for landlord Charter Hall and major brands including L’Oréal, Sheridan, Bonds, Dermalogica and Jurlique asked about their position in the pecking order of creditors, how to process refunds and whether they could retrieve their stock.
“We need clear answers,” said European fashion and footwear label director Rocco Mascitelli in the meeting. Receiver and manager FTI Consulting, in charge of David Jones’ day-to-day business, was not responding to his queries about retrieving stock, he said.
“We don’t seem to get any answers. So, although you guys [McGrathNicol] are not in charge of this process, we’re not getting any answers from FTI.”
McGrathNicol partners Jason Preston, Shaun Fraser, Jacinta Nielsen and Matthew Hutton, who have been appointed voluntary administrators, are running the sale process.
Fraser, McGrathNicol’s founding…
Opening of the article, excerpted from The Age. To read the rest, open the article on the publisher's site.
MarketNews shows the headline and summary published by the outlet. The full article is on the publisher's website. (www.theage.com.au)